Your Trusted Roof experts
Can Insurers Deny Roof Claims? Yes. Here's Why.
A denial is a decision, not always the final word. Here's what drives it and what to do next.
Call or TEXT now832-384-4420What to expect
A storm can leave your roof looking mostly normal from the driveway while shingles, flashing, vents, and soft metal components tell a very different story up close. So, can insurers deny roof claims? Yes. But a denial does not automatically mean your roof is fine, your policy offers no help, or you should pay for everything out of pocket without asking questions. For Greater Houston homeowners, the difference often comes down to cause, timing, policy language, and proof.
Fort Bend County and the Houston metro see above-average hail and wind events every year. That means more claims, more adjusters, and, unfortunately, more denials based on incomplete inspections or documentation gaps. Understanding why carriers say no is the first step toward knowing whether that answer should stand.
Why Insurers Deny Roof Claims
Not every denial is a dead end: but you need to understand what's behind it.
Common Reasons
The Four Situations That Lead to a Denial
Wear and Tear vs. Storm Damage
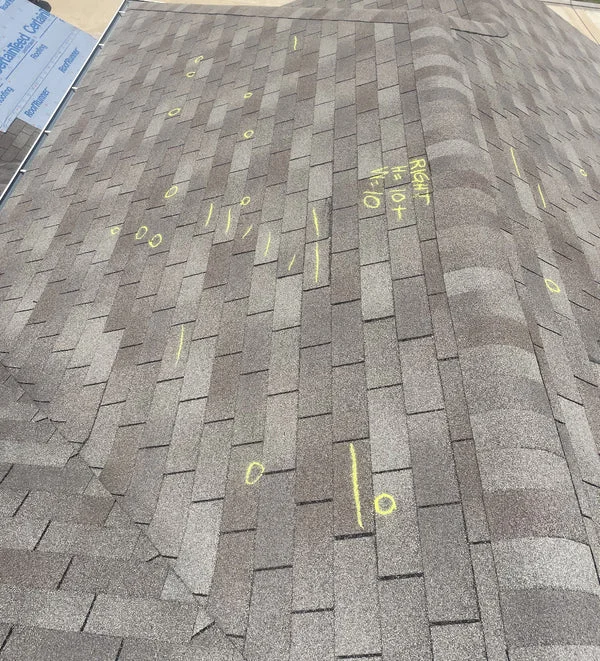
This is the most common dividing line. Granule loss, brittle shingles, failed sealant, rust, improper installation, and long-term leaks are typically categorized as maintenance or age-related conditions. Standard homeowners policies do not cover maintenance problems. Hail strikes, wind-lifted shingles, impact damage to vents, fallen limbs, and water intrusion caused by a covered storm event are a different matter. The challenge: both conditions can exist on the same roof, and adjusters are not always thorough enough to separate them. If you suspect your claim mixed the two, an independent roof inspection report can help clarify what belongs to which category.
The Carrier Cannot Verify the Date of Loss
Texas weather moves fast, and homeowners often do not notice roof damage until weeks or months after a storm. By then, an adjuster may have trouble connecting the observed condition to a specific event. If the claim lists a vague date, or if the damage appears weathered rather than fresh, the carrier may question causation. That is where timely documentation helps. NOAA storm reports can establish that hail or damaging winds occurred near your property. Photos of damaged screens, gutters, and exterior surfaces, taken shortly after a storm, give the adjuster something to work with. For a deeper look at how to build that file, see our guide on how to document roof damage.
The Damage Falls Below Your Deductible
A deductible is not a denial, even though it can feel like one. If the covered repair amount is $2,000 and your wind or hail deductible is $3,000, the carrier may acknowledge covered damage but issue no payment. In Texas, percentage deductibles can be substantial because they are often based on the home's insured value rather than a flat dollar amount. Before filing, review your declarations page so you know whether you have a separate wind, hail, named-storm, or hurricane deductible.
Policy Exclusions or Coverage Limits Apply
Policies vary. Some have cosmetic-damage exclusions for metal components. Others limit payment for older roofs, use actual cash value rather than replacement cost value, or exclude certain losses related to improper maintenance, prior damage, or water that entered over time. Replacement cost value policies generally pay the depreciated amount first, then release recoverable depreciation after qualifying repairs are completed. Actual cash value policies do not release that remainder. If your policy pays ACV and your roof is fifteen years old, the payout may cover only a fraction of the replacement cost.
After a Denial
What to Do When a Roof Claim Is Denied
When the Carrier Approves Part of the Damage
Be Proactive
How to Build a Stronger Claim Before Trouble Starts
The strongest claims usually begin before the adjuster arrives.
Document immediately after the storm
Dated photos of your roof, gutters, fences, windows, and exterior surfaces taken the same day create a timestamp that adjusters cannot easily dismiss.
Keep a repair and maintenance file
Receipts and warranties for prior roof work establish a maintenance history that supports your claim and shows the damage is new, not pre-existing.
Get a written inspection report
A professional report with labeled photos and measurements gives the carrier a specific document to respond to. Not just a homeowner's word.
Track all correspondence and claim records
Storm dates, NOAA hail reports, temporary mitigation records, and every carrier communication belong in one folder from the moment you open a claim.
Straight from Google
What Reviewers Say About Working Through the Process
Working with PPB Roofs & Restoration was a smooth process from start to finish. Communication was great the entire time, and they kept us updated throughout the project. The crew was professional, on time, and did an excellent job cleaning up afterward. The roof came out great and I’m very impressed. Definitely a company I would recommend to others.
 Miranda Gonzales
PPB Roof and Restoration were excellent on my roof replacement. They were not high pressure, nor did they try to up-sell on products I didn’t need. Their prices were more than fair. The entire process was easy and very straightforward. They completed our entire roof in one day. David my project manager and AJ the owner were both very helpful and responsive. We are very happy with the results and strongly recommend the company.
 Bert & Diane Molina
Ayden Diaz and Prime Property Builders offered a complimentary inspection of my roof when they were doing some repairs in my neighborhood. They were nice and honest. They did not find much problem with my roof except normal wears and some nail holes. They came back the other day and caulked the holes for free to prevent possible leaking as heavy rains forecasted to come next day! I do appreciate their honest, consideration, and community spirit! I would do business with them in the future.
 Xiao Wang
I was approached by several other roofing companies that did not help with my insurance claim. So, when AJ Diaz stopped by, it was difficult to believe that he would be different. However, he was very knowledgeable about the entire insurance process and about roofing products, so I let him start the process. I am very happy that I did. He walked me through every step of the process and kept me informed of where my claim stood and what I needed to do next. He was on-site during the insurance company inspection and helped me find an independent inspector when my claim went to arbitration. He was happy to take the time to answer all my many many questions. Once my claim was finally approved, he helped me select roofing products that were best for my house, had a good quality guarantee, and the color that I wanted. He was able to explain the difference in the products and how they were installed. So, I feel like I made an informed decision. I also had gutters replaced that made everything look so good with the new roof. See the pictures! AJ was also on-site during the installation and came back afterwards to make sure I was happy. I am so happy by the way everything turned out. I highly recommend him and his company.
 Carol Sumrall
I am highly satisfied with the work completed by this company in the Houston area. From initial consultation through project completion, the entire process was managed with professionalism, efficiency, and attention to detail. What distinguished their service was the level of support provided after the installation. The team remained proactive in their follow-up, ensuring that all aspects of the project were functioning properly and that I was fully satisfied with the outcome. I would confidently recommend their services to anyone in Katy or the greater Houston area seeking high-quality roofing solutions and reliable, customer-focused service.
 Avery Callejo
Extremely happy with the service provided by Ayden and PPB PATIO & ROOF folks. Very reliable and honest. Will definitely recommend them to anyone looking to replace their roof.
 KaiSoon Tan
Common Questions About Roof Claim Denials
Still have a question?
Ask the team directly. We pick up, and a straight answer costs nothing.
Can I appeal a denied roof claim in Texas?
How long do I have to file a roof claim after a storm in Texas?
What is the difference between ACV and RCV on a roof claim?
What does a cosmetic damage exclusion mean for my claim?
Will filing a roof claim raise my homeowners insurance premium?
A Denial Is a Decision: Not Always the Final Word
Get the full picture before you accept a denial.