Your Trusted Roof experts
How to File a Roof Claim After Texas Storm Damage
A calm, step-by-step walkthrough for Fort Bend County homeowners dealing with hail, wind, or hurricane damage.
Call or TEXT now832-384-4420What to expect
The day after a Texas hailstorm, a roof can look perfectly fine from the driveway while carrying damage that shortens its life, opens the door to leaks, or becomes an expensive surprise months later. Knowing how to file a roof claim gives you a calmer, more organized path forward, and helps you protect one of your biggest investments without guessing what comes next.
A roof insurance claim is a request for your carrier to evaluate covered damage. It is not a guarantee of a new roof, and it is not something a contractor should control on your behalf. This guide walks through each step so you go into the process with clear expectations, from the day after the storm through the final payment.
Step One
Start With Safety and Prevent Further Damage
Step Two
Check Your Policy Before You File
This step matters because filing a claim becomes part of your insurance history: even if the claim is never approved.
Document the Storm and the Damage
Photograph every elevation
Take wide photos of each side of the home, then move closer to capture visible roof, gutter, siding, fence, window-screen, and outdoor equipment damage. Include the date stamp when possible and do not edit images in a way that changes what they show.
Document interior signs
Photograph water stains, wet insulation, ceiling bubbling, or any other interior evidence of water intrusion. These images help establish that roof damage translated to actual loss inside the home.
Establish the storm date
Record the storm date and your address. NOAA storm reports are a primary source for verifying weather event timing and type. Your carrier will reference this data, so it helps to have it yourself before you file.
Keep a written record
Note when you first noticed damage, what steps you took, who you spoke to, and when. A simple running document, even a dated text thread, builds a factual timeline that supports your claim if questions come up later.
Our Process
How to File With Your Insurance Carrier
Once you have reason to believe covered storm damage exists, contact your insurer using the phone number on your policy or insurance card. Most carriers allow you to start online or by phone. Give a factual description: the storm date, the type of weather, when you noticed the damage, and any emergency steps taken. Avoid guessing at the repair cost or stating upfront that you need a full replacement. Let the adjuster determine scope. Do not let a contractor file a claim in your name or represent themselves as your public adjuster unless they are licensed in Texas for that role. A reputable contractor can inspect the roof, explain the damage, prepare an estimate, and be present during the adjuster visit to discuss roofing conditions. The policyholder stays in control of the claim.
Call Your Carrier
Use the number on your policy or insurance card. Describe the storm date, weather type, and damage you observed. Do not estimate the repair cost.
Schedule the Adjuster Inspection
The carrier will assign an adjuster to inspect. Have your photos, receipts, and storm date documentation ready. You may have a contractor present to walk the roof alongside the adjuster.
Review the Scope of Loss
Once the adjuster submits their report, you will receive a claim decision that lists covered items and amounts. Read the full scope, not just the total.
What to Watch for in the Adjuster Inspection
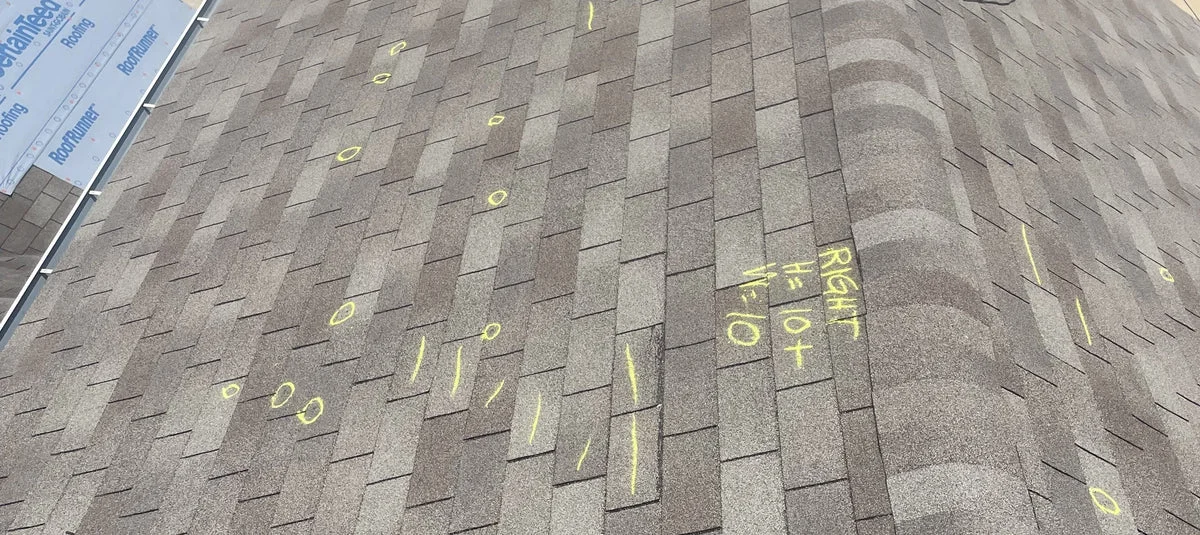
Reading the Claim Decision
Review Every Line Item
Confirm that shingles, underlayment, flashing, gutters, and code-upgrade items are listed. Omissions on a scope of loss mean money left on the table.
Understand the Depreciation Math
RCV policies release recoverable depreciation after the work is completed and final documentation is submitted. Track this. It is often a second check that some homeowners never request.
Know Your Appeal Rights
A denial based on wear and tear can be challenged with documented storm evidence. Stay factual, meet all deadlines, and keep copies of every document you send and receive.
Choose Repairs That Address the Real Damage
Straight from Google
What Reviewers Say About Filing With PPB's Help
Working with PPB Roofs & Restoration was a smooth process from start to finish. Communication was great the entire time, and they kept us updated throughout the project. The crew was professional, on time, and did an excellent job cleaning up afterward. The roof came out great and I’m very impressed. Definitely a company I would recommend to others.
 Miranda Gonzales
PPB Roof and Restoration were excellent on my roof replacement. They were not high pressure, nor did they try to up-sell on products I didn’t need. Their prices were more than fair. The entire process was easy and very straightforward. They completed our entire roof in one day. David my project manager and AJ the owner were both very helpful and responsive. We are very happy with the results and strongly recommend the company.
 Bert & Diane Molina
Ayden Diaz and Prime Property Builders offered a complimentary inspection of my roof when they were doing some repairs in my neighborhood. They were nice and honest. They did not find much problem with my roof except normal wears and some nail holes. They came back the other day and caulked the holes for free to prevent possible leaking as heavy rains forecasted to come next day! I do appreciate their honest, consideration, and community spirit! I would do business with them in the future.
 Xiao Wang
I was approached by several other roofing companies that did not help with my insurance claim. So, when AJ Diaz stopped by, it was difficult to believe that he would be different. However, he was very knowledgeable about the entire insurance process and about roofing products, so I let him start the process. I am very happy that I did. He walked me through every step of the process and kept me informed of where my claim stood and what I needed to do next. He was on-site during the insurance company inspection and helped me find an independent inspector when my claim went to arbitration. He was happy to take the time to answer all my many many questions. Once my claim was finally approved, he helped me select roofing products that were best for my house, had a good quality guarantee, and the color that I wanted. He was able to explain the difference in the products and how they were installed. So, I feel like I made an informed decision. I also had gutters replaced that made everything look so good with the new roof. See the pictures! AJ was also on-site during the installation and came back afterwards to make sure I was happy. I am so happy by the way everything turned out. I highly recommend him and his company.
 Carol Sumrall
I am highly satisfied with the work completed by this company in the Houston area. From initial consultation through project completion, the entire process was managed with professionalism, efficiency, and attention to detail. What distinguished their service was the level of support provided after the installation. The team remained proactive in their follow-up, ensuring that all aspects of the project were functioning properly and that I was fully satisfied with the outcome. I would confidently recommend their services to anyone in Katy or the greater Houston area seeking high-quality roofing solutions and reliable, customer-focused service.
 Avery Callejo
Extremely happy with the service provided by Ayden and PPB PATIO & ROOF folks. Very reliable and honest. Will definitely recommend them to anyone looking to replace their roof.
 KaiSoon Tan
Common Questions About Roof Insurance Claims
Still have a question?
Ask the team directly. We pick up, and a straight answer costs nothing.
Can a contractor file a claim on my behalf?
What if the storm date is unclear?
What is recoverable depreciation?
Does filing a claim affect my premium?
What is a wind or hail deductible in Texas?
We Help Greater Houston Homeowners Through Every Step
- Richmond, TX
- Sugar Land, TX
- Katy, TX
- Rosenberg, TX
- Fulshear, TX
- Missouri City, TX
- Stafford, TX
- Pearland, TX
- Bellaire, TX
- Meadows Place, TX
- Fort Bend County