Your Trusted Roof experts
Roof Depreciation Insurance Guide for Texas Homes
What that depreciation line on your insurance estimate actually means, and what you can do about it.
Call or TEXT now832-384-4420What to expect
A storm can leave your roof with obvious missing shingles, or with damage that only shows up later as a stain on the ceiling. Then the insurance estimate arrives, and one line item raises a bigger question than the repair itself: depreciation. This guide explains what that number means, why it can be substantial on an older Texas roof, and what must happen before some of that money is paid back to you.
If you are working through a storm claim right now, a professional roof inspection report is the fastest way to understand what the carrier has, and has not, accounted for. But first, it helps to understand how depreciation works and how your policy type determines whether you can recover it.
What Roof Depreciation Means on an Insurance Claim
Policy Types
ACV vs. RCV: The Difference That Changes Your Out-of-Pocket ACV vs. RCV
Actual Cash Value (ACV)
ACV pays the depreciated value of the damaged roof. The insurer starts with the replacement cost, subtracts depreciation, then applies your deductible. The depreciation typically stays withheld, permanently. Using the $20,000 example: $20,000 minus $6,000 depreciation minus a $2,500 deductible leaves an insurance payment of roughly $11,500. The remaining $6,000 does not come back.
Replacement Cost Value (RCV)
RCV pays the cost to restore covered damage with comparable materials, less your deductible. The insurer may issue an initial payment based on actual cash value, then release the withheld depreciation, called recoverable depreciation, after the work is completed and required documentation is submitted. Under an RCV policy, that $6,000 can come back to you once the job is done and paperwork filed.
Our Process
How Recoverable Depreciation Gets Released
Many homeowners see the first insurance payment and assume it is the final settlement. With an RCV claim, it often is not. The carrier holds back depreciation until it has proof that covered repairs or replacement were completed. The details vary by policy and carrier, but the general sequence is consistent.
Receive the Estimate and Initial Payment
The carrier issues its scope of loss and an initial check based on actual cash value. Read the line-item detail carefully, coverage basis, deductible, depreciation amount, and any exclusions should all be listed.
Complete the Covered Work
The roof is replaced or repaired to the scope covered by the policy. Work must be completed within the timeframe specified in the policy, missing that deadline can forfeit the recoverable depreciation entirely.
Submit Documentation and Recover the Balance
After completion, you submit the final invoice and any required paperwork. The carrier reviews it and releases the withheld depreciation, minus your deductible if it has not already been applied. This is the recoverable depreciation payment.
What RCV Coverage Does Not Cover
Claim Accuracy
Why the Insurance Estimate May Not Match the Real Scope
What Carriers Use to Calculate Depreciation
Roof Age
The older the roof, the higher the depreciation. A 20-year-old roof may be depreciated significantly even if it was structurally sound before the storm. Some carriers depreciate materials differently from labor.
Material Type
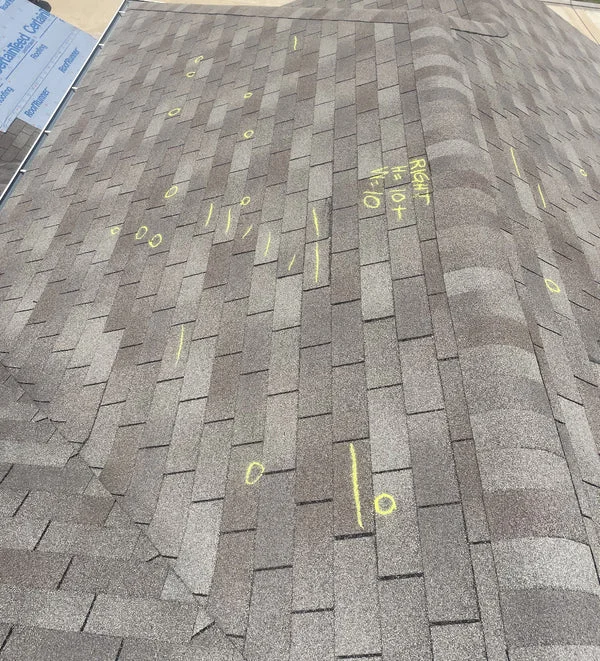
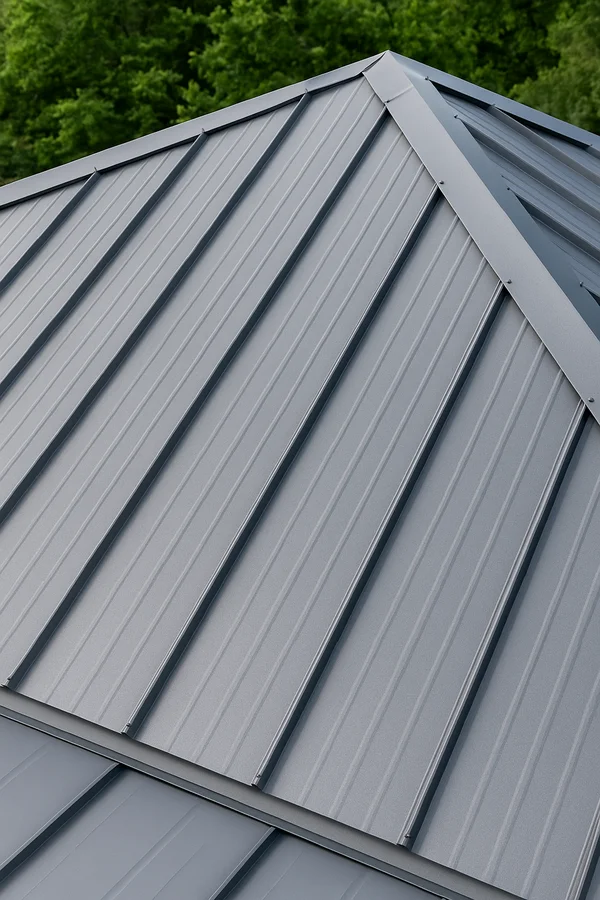
Different roofing materials carry different expected lifespans. A 3-tab shingle is depreciated faster than an architectural shingle. Metal roofing typically depreciates more slowly. The carrier assigns value based on what was there, not what you would prefer to have.
Condition at Time of Loss
Prior wear, granule loss, and documented maintenance history can all affect the depreciation calculation. A roof with pre-existing damage may be depreciated more heavily than one in clean condition before the storm.
Policy Terms
Some policies cap depreciation. Others exclude certain components from depreciation entirely. The only way to know where you stand is to read your declarations page and ask direct questions, or have someone who knows the process review it with you.
Before the Next Storm
How to Protect Your Claim Before and After a Storm
Document Before Damage Occurs
An annual roof inspection gives you a dated, photographic baseline. If a storm hits and the carrier argues pre-existing damage, a clean pre-storm inspection is evidence on your side.
Act Immediately After a Storm
Photograph visible damage from the ground before anything is touched. If water is entering the structure, emergency tarp protection limits further loss and demonstrates you mitigated damage, which is a policy requirement. Call your carrier to open the claim.
Get an Independent Assessment
Before the adjuster visit, have a contractor walk the roof. A written assessment gives you a reference point. If the adjuster's scope is materially different, you have documented grounds to request a re-inspection or supplemental review.
When Depreciation Deserves a Second Look
Straight from Google
What Homeowners Say After Working Through a Claim With Us
Working with PPB Roofs & Restoration was a smooth process from start to finish. Communication was great the entire time, and they kept us updated throughout the project. The crew was professional, on time, and did an excellent job cleaning up afterward. The roof came out great and I’m very impressed. Definitely a company I would recommend to others.
 Miranda Gonzales
PPB Roof and Restoration were excellent on my roof replacement. They were not high pressure, nor did they try to up-sell on products I didn’t need. Their prices were more than fair. The entire process was easy and very straightforward. They completed our entire roof in one day. David my project manager and AJ the owner were both very helpful and responsive. We are very happy with the results and strongly recommend the company.
 Bert & Diane Molina
Ayden Diaz and Prime Property Builders offered a complimentary inspection of my roof when they were doing some repairs in my neighborhood. They were nice and honest. They did not find much problem with my roof except normal wears and some nail holes. They came back the other day and caulked the holes for free to prevent possible leaking as heavy rains forecasted to come next day! I do appreciate their honest, consideration, and community spirit! I would do business with them in the future.
 Xiao Wang
I was approached by several other roofing companies that did not help with my insurance claim. So, when AJ Diaz stopped by, it was difficult to believe that he would be different. However, he was very knowledgeable about the entire insurance process and about roofing products, so I let him start the process. I am very happy that I did. He walked me through every step of the process and kept me informed of where my claim stood and what I needed to do next. He was on-site during the insurance company inspection and helped me find an independent inspector when my claim went to arbitration. He was happy to take the time to answer all my many many questions. Once my claim was finally approved, he helped me select roofing products that were best for my house, had a good quality guarantee, and the color that I wanted. He was able to explain the difference in the products and how they were installed. So, I feel like I made an informed decision. I also had gutters replaced that made everything look so good with the new roof. See the pictures! AJ was also on-site during the installation and came back afterwards to make sure I was happy. I am so happy by the way everything turned out. I highly recommend him and his company.
 Carol Sumrall
I am highly satisfied with the work completed by this company in the Houston area. From initial consultation through project completion, the entire process was managed with professionalism, efficiency, and attention to detail. What distinguished their service was the level of support provided after the installation. The team remained proactive in their follow-up, ensuring that all aspects of the project were functioning properly and that I was fully satisfied with the outcome. I would confidently recommend their services to anyone in Katy or the greater Houston area seeking high-quality roofing solutions and reliable, customer-focused service.
 Avery Callejo
Extremely happy with the service provided by Ayden and PPB PATIO & ROOF folks. Very reliable and honest. Will definitely recommend them to anyone looking to replace their roof.
 KaiSoon Tan
Common Questions About Roof Depreciation and Insurance Claims
Still have a question?
Ask the team directly. We pick up, and a straight answer costs nothing.
Can I upgrade my roof materials and still get full insurance coverage?
What happens if I have ACV coverage and the claim doesn't cover the full replacement?
How long do I have to file for recoverable depreciation after completing the work?
Is my deductible affected by how much depreciation the carrier assigns?
Should I sign anything before I understand the full settlement?
Start here
Serving Texas Homeowners Through Every Step of the Claim
PPB Roofs & Restoration is a Latinx-owned, insured roofing contractor based in Richmond, TX, serving Fort Bend County and the greater Houston area. If you have questions about a claim, need a second look at an insurance estimate, or want a professional inspection before the next storm season, we are available Monday through Saturday. Call (832) 384-4420 or use the form below.
832-384-4420Mon–Sat: 9 AM – 7 PM · Sun: Closed
Or send it in writing