Your Trusted Roof experts
Roofing Estimate Versus Insurance Scope Explained
Two documents, one roof. Here is why they often say different things and what to do about it.
Call or TEXT now832-384-4420What to expect
A storm can leave your roof looking mostly fine from the driveway while loosened shingles, bruised asphalt, damaged vents, and compromised flashing tell a different story up close. That is where the roofing estimate versus insurance scope conversation starts. Homeowners often expect the two documents to match line for line. Sometimes they do. Often, especially after hail or wind damage in Greater Houston, they do not.
Neither document is automatically wrong. Each comes from a different starting point, a different set of observations, and a different purpose. Understanding what each one is, and where they are likely to diverge, saves time, prevents surprises, and keeps your roof replacement project moving forward without unnecessary conflict.
What a Roofing Estimate Covers
What an Insurance Scope Covers
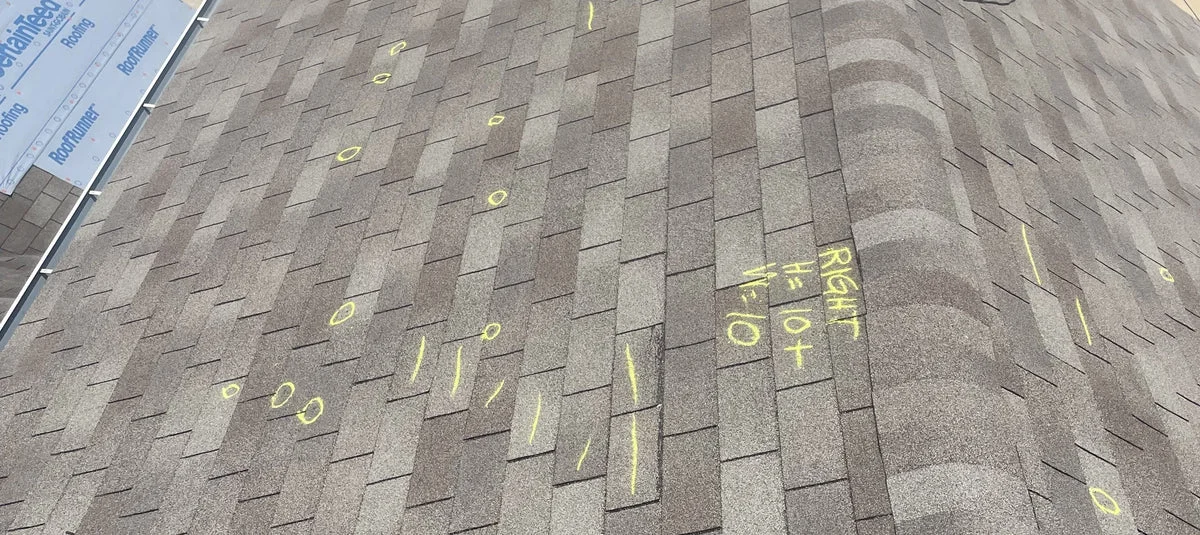
Gap Analysis
Where Estimates and Scopes Diverge
Most initial scopes are written from a single adjuster visit: and a roof is a layered system that does not always reveal everything from the surface.
Scope and Quantity
The adjuster and contractor measured different roof areas, or counted different slopes, valleys, ridges, and waste factors. A small measurement difference multiplies quickly across a full system.
Missed Accessories
Damage to vents, flashing, gutters, skylights, or soft metals was not clearly documented or tied to the storm event during the initial adjustment.
Code Upgrade Requirements
Local building-code upgrades required for a safe replacement were not included in the initial scope. Code compliance is not optional, it affects materials, fastening patterns, and sometimes decking.
Concealed Conditions
Decking damage, rot, or other conditions were discovered only after tear-off. These cannot always be seen or documented before the old roof comes off.
Our Process
How to Compare the Two Documents
Start with the basics, then go line by line.
Start With the Basics
Confirm the property address, date of loss, roof type, number of layers being removed, and the square footage or roofing squares shown on each document. A small measurement difference creates a meaningful difference in material and labor costs.
Go Line by Line
Compare the full roof system: underlayment, starter strips, field shingles, ridge cap, flashing, pipe boots, ventilation, and decking. Note every item that appears on one document but not the other. That list is the starting point for a supplement request.
Separate Policy Coverage From Project Scope
Insurance generally pays to restore covered damage to like-kind condition. Premium shingle upgrades, redesigned drainage, or additional work you want done are legitimate choices. They just need to be quoted honestly as homeowner-selected improvements, separate from the covered restoration.
Supplements
Supplements Are a Normal Part of Storm Restoration
Questions to Ask Before You Sign
Before you approve any work, get clear answers to these.
Is this proposal based on the insurance scope, an independent inspection, or both?
You need to know what your contractor actually inspected, and whether they have seen the carrier's scope or are working from their own measurements only.
What items differ between the two documents, and why?
A contractor who cannot explain the differences line by line is not prepared to support a supplement request if one becomes necessary.
Could the price change if concealed damage is found after tear-off?
Decking repairs are the most common post-tear-off addition. Know in advance how that is handled, per-sheet pricing is standard and should be spelled out before work starts.
What warranties apply, and who handles the final documentation for payment?
Recoverable depreciation requires proof of completion. Know who is responsible for submitting that documentation to your carrier before the project closes.
When the Scope Is Right: and When It Needs Another Look
What Reviewers Say
Richmond Homeowners on the Claims Process
Working with PPB Roofs & Restoration was a smooth process from start to finish. Communication was great the entire time, and they kept us updated throughout the project. The crew was professional, on time, and did an excellent job cleaning up afterward. The roof came out great and I’m very impressed. Definitely a company I would recommend to others.
 Miranda Gonzales
PPB Roof and Restoration were excellent on my roof replacement. They were not high pressure, nor did they try to up-sell on products I didn’t need. Their prices were more than fair. The entire process was easy and very straightforward. They completed our entire roof in one day. David my project manager and AJ the owner were both very helpful and responsive. We are very happy with the results and strongly recommend the company.
 Bert & Diane Molina
Ayden Diaz and Prime Property Builders offered a complimentary inspection of my roof when they were doing some repairs in my neighborhood. They were nice and honest. They did not find much problem with my roof except normal wears and some nail holes. They came back the other day and caulked the holes for free to prevent possible leaking as heavy rains forecasted to come next day! I do appreciate their honest, consideration, and community spirit! I would do business with them in the future.
 Xiao Wang
I was approached by several other roofing companies that did not help with my insurance claim. So, when AJ Diaz stopped by, it was difficult to believe that he would be different. However, he was very knowledgeable about the entire insurance process and about roofing products, so I let him start the process. I am very happy that I did. He walked me through every step of the process and kept me informed of where my claim stood and what I needed to do next. He was on-site during the insurance company inspection and helped me find an independent inspector when my claim went to arbitration. He was happy to take the time to answer all my many many questions. Once my claim was finally approved, he helped me select roofing products that were best for my house, had a good quality guarantee, and the color that I wanted. He was able to explain the difference in the products and how they were installed. So, I feel like I made an informed decision. I also had gutters replaced that made everything look so good with the new roof. See the pictures! AJ was also on-site during the installation and came back afterwards to make sure I was happy. I am so happy by the way everything turned out. I highly recommend him and his company.
 Carol Sumrall
I am highly satisfied with the work completed by this company in the Houston area. From initial consultation through project completion, the entire process was managed with professionalism, efficiency, and attention to detail. What distinguished their service was the level of support provided after the installation. The team remained proactive in their follow-up, ensuring that all aspects of the project were functioning properly and that I was fully satisfied with the outcome. I would confidently recommend their services to anyone in Katy or the greater Houston area seeking high-quality roofing solutions and reliable, customer-focused service.
 Avery Callejo
Extremely happy with the service provided by Ayden and PPB PATIO & ROOF folks. Very reliable and honest. Will definitely recommend them to anyone looking to replace their roof.
 KaiSoon Tan
Common Questions About Estimates and Insurance Scopes
Still have a question?
Ask the team directly. We pick up, and a straight answer costs nothing.
Does my contractor have to match the insurance scope exactly?
What is recoverable depreciation and when do I receive it?
Can the price change after the project starts?
How long does a supplement request take?
What if I want a better shingle than what the scope covers?
Free Roof Inspection: Fort Bend County and Greater Houston
If a storm has hit your neighborhood and you are not sure whether to file a claim, start with an inspection.