Your Trusted Roof experts
The Truth About Roof Insurance Claims in Texas
What most homeowners learn too late, and how to protect your claim before the damage gets worse.
Call or TEXT now832-384-4420What to expect
Most roof replacements don't happen because someone planned ahead. They happen because waiting got expensive. In Texas, roofs don't fail quietly, they fail slowly, then all at once, usually during a storm, when emergency repair options are limited and insurance questions start stacking up.
This guide covers what Fort Bend County homeowners need to understand about the insurance process before a claim becomes complicated, and what to do the moment storm damage is suspected.
The Damage You Don't See Is the One That Gets You
Roof failure is rarely sudden. It's a slow process that accelerates when you're not looking.
Insurance Reality
Delays Can Cost You Coverage
Insurance companies care when damage happened, not when you noticed it.
Granule Loss
Aging shingles lose granules that protect the asphalt layer from UV exposure. Once that layer degrades, the shingle's lifespan drops fast, and so does your claim value.
Seal Strip Failure
Seal strips keep shingles bonded against wind lift. When they weaken, shingles become vulnerable to the next storm, and insurers may classify the resulting damage as pre-existing.
Flashing Separation
Where the roof meets walls, chimneys, and vents, flashing holds the seal. Once it begins separating, moisture follows. Interior damage is usually next.
Denied or Reduced Claims
If storm damage occurred months or years before a claim is filed, carriers may reduce coverage or deny portions of the claim entirely. What could have been a full replacement becomes partial repairs, or out-of-pocket costs. Learn more about how insurers deny claims.
Emergency Replacements Are Always More Expensive
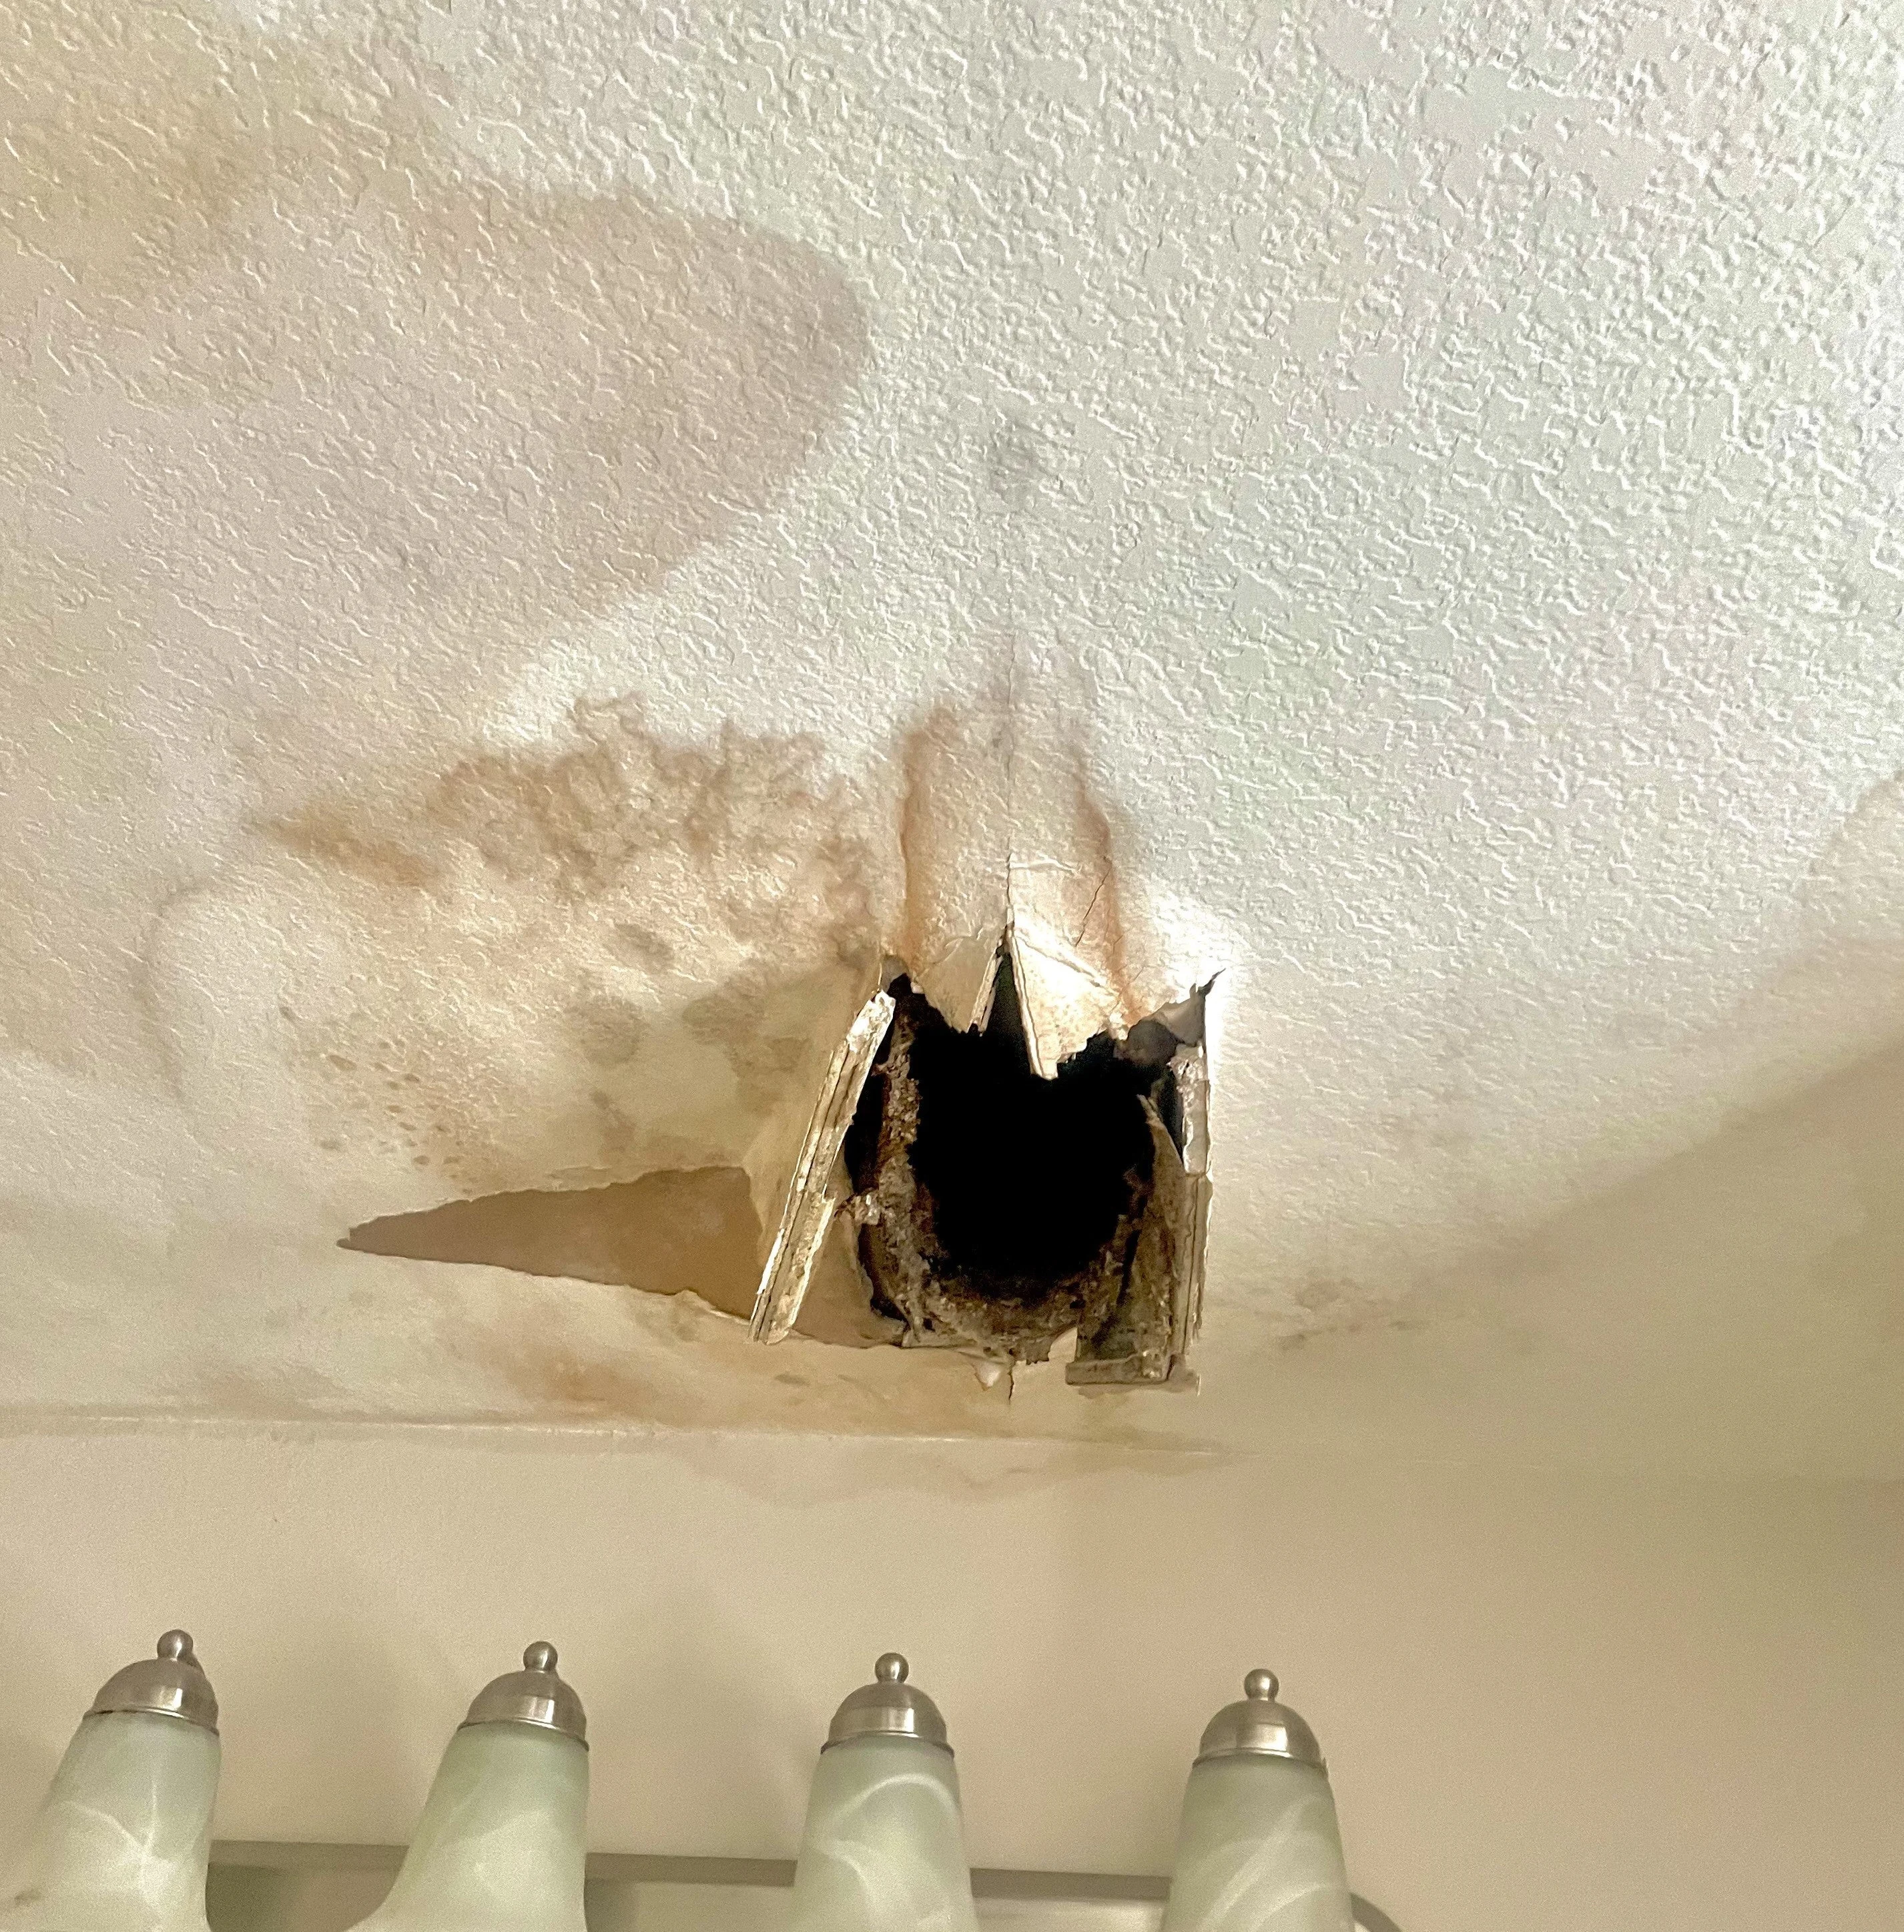
A roofing problem that waits long enough becomes a drywall problem, a mold problem, or both.
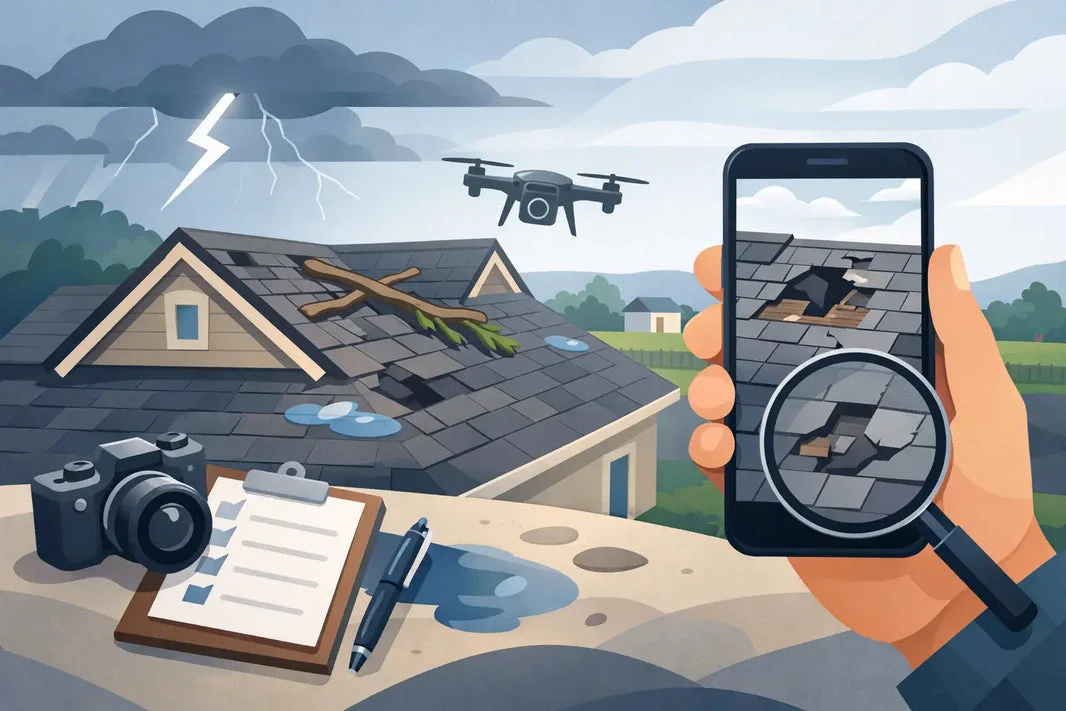
What to Know
How the Insurance Process Actually Works
The insurance process from start to finish is more manageable when you know what's coming. Here's what a well-documented storm damage claim looks like.
Step 1: Get a Professional Inspection
Before you call your carrier, get a documented inspection from an insured contractor. This establishes the damage on paper, with photos, and gives you a baseline for what the adjuster should be finding.
Step 2: File Promptly, Not Immediately
File as soon as the damage is documented. Not before you understand what's there. A premature or incomplete claim can create problems if the adjuster finds more damage later. Know what you're filing for.
Step 3: Be Present for the Adjuster Visit
Have your contractor present during the insurance company's inspection. An experienced roofing contractor can walk the roof alongside the adjuster, point out documented damage, and ensure nothing is missed.
What Impact Shingles Mean for Your Insurance Premium
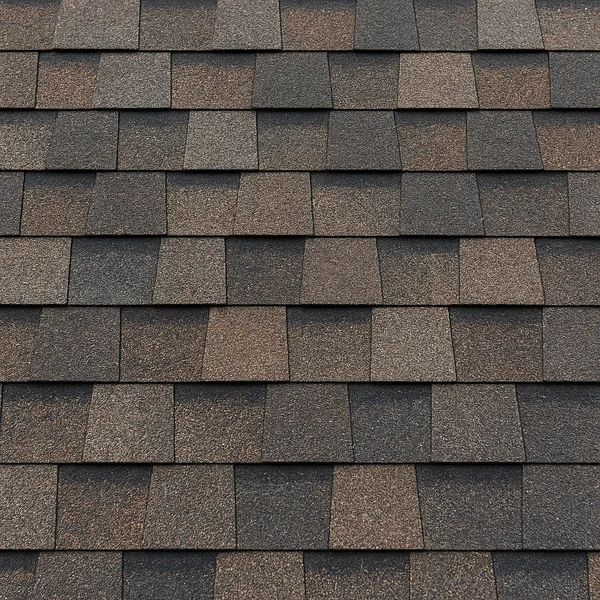
What a Hail Inspection Actually Documents
Planned Replacement vs. Waiting It Out
You Choose the Timeline
Planned replacements happen on a schedule that works for your household, not during the next rainstorm when your living room ceiling is wet.
You Choose the Materials
When you're not under emergency pressure, you can review shingle samples, compare warranty tiers, and make the choice that fits the house. Not just what's on the truck.
You Control the Insurance Conversation
A proactively documented roof gives you leverage with your carrier. An emergency replacement after years of deferred maintenance gives them leverage over you.
About PPB
We Help You Understand the Roof Before the Claim
PPB Roofs & Restoration is a Latinx-owned, insured roofing contractor serving Richmond and Greater Houston. We've guided homeowners through straightforward replacements and through contested insurance claims that went to arbitration, and we stay on-site for both.
-
Free inspection with written documentation
You get a real report, not a verbal opinion
-
On-site during your insurance adjuster's visit
We walk the roof alongside them so nothing gets missed
-
No-pressure shingle selection
We bring samples and explain the difference. We don't upsell
-
Insured Texas contractor
Permanently based in Richmond, not a post-storm out-of-state crew
Ready to Know Where Your Roof Stands?
A free inspection takes less than an hour. The information you get from it can protect your insurance claim for years.