Your Trusted Roof experts
Roof Insurance Claims: What Texas Homeowners Need to Know
A step-by-step guide to protecting your home and your claim after a Texas storm.
Call or TEXT now832-384-4420What to expect
The day after a Texas hailstorm, your roof may look fine from the driveway. That is exactly why a roof insurance claim can become stressful weeks later, when a water stain appears on the ceiling or granules start collecting in the gutters. Storm damage is not always visible from the ground, and waiting too long to investigate can leave you with fewer options and a larger repair bill.
At PPB Roofs & Restoration, we believe homeowners deserve clear answers before they make a major decision. A claim is not a free-roof promise, and not every mark on a shingle is covered damage. It is a process for documenting a sudden covered loss, understanding your policy, and protecting the home you have worked hard to build. This guide walks through each step, plainly, without pressure.
Step 1
Start With Safety and Document What You Can
The hours right after a storm are your best window for gathering the evidence your claim will depend on.
Step 2
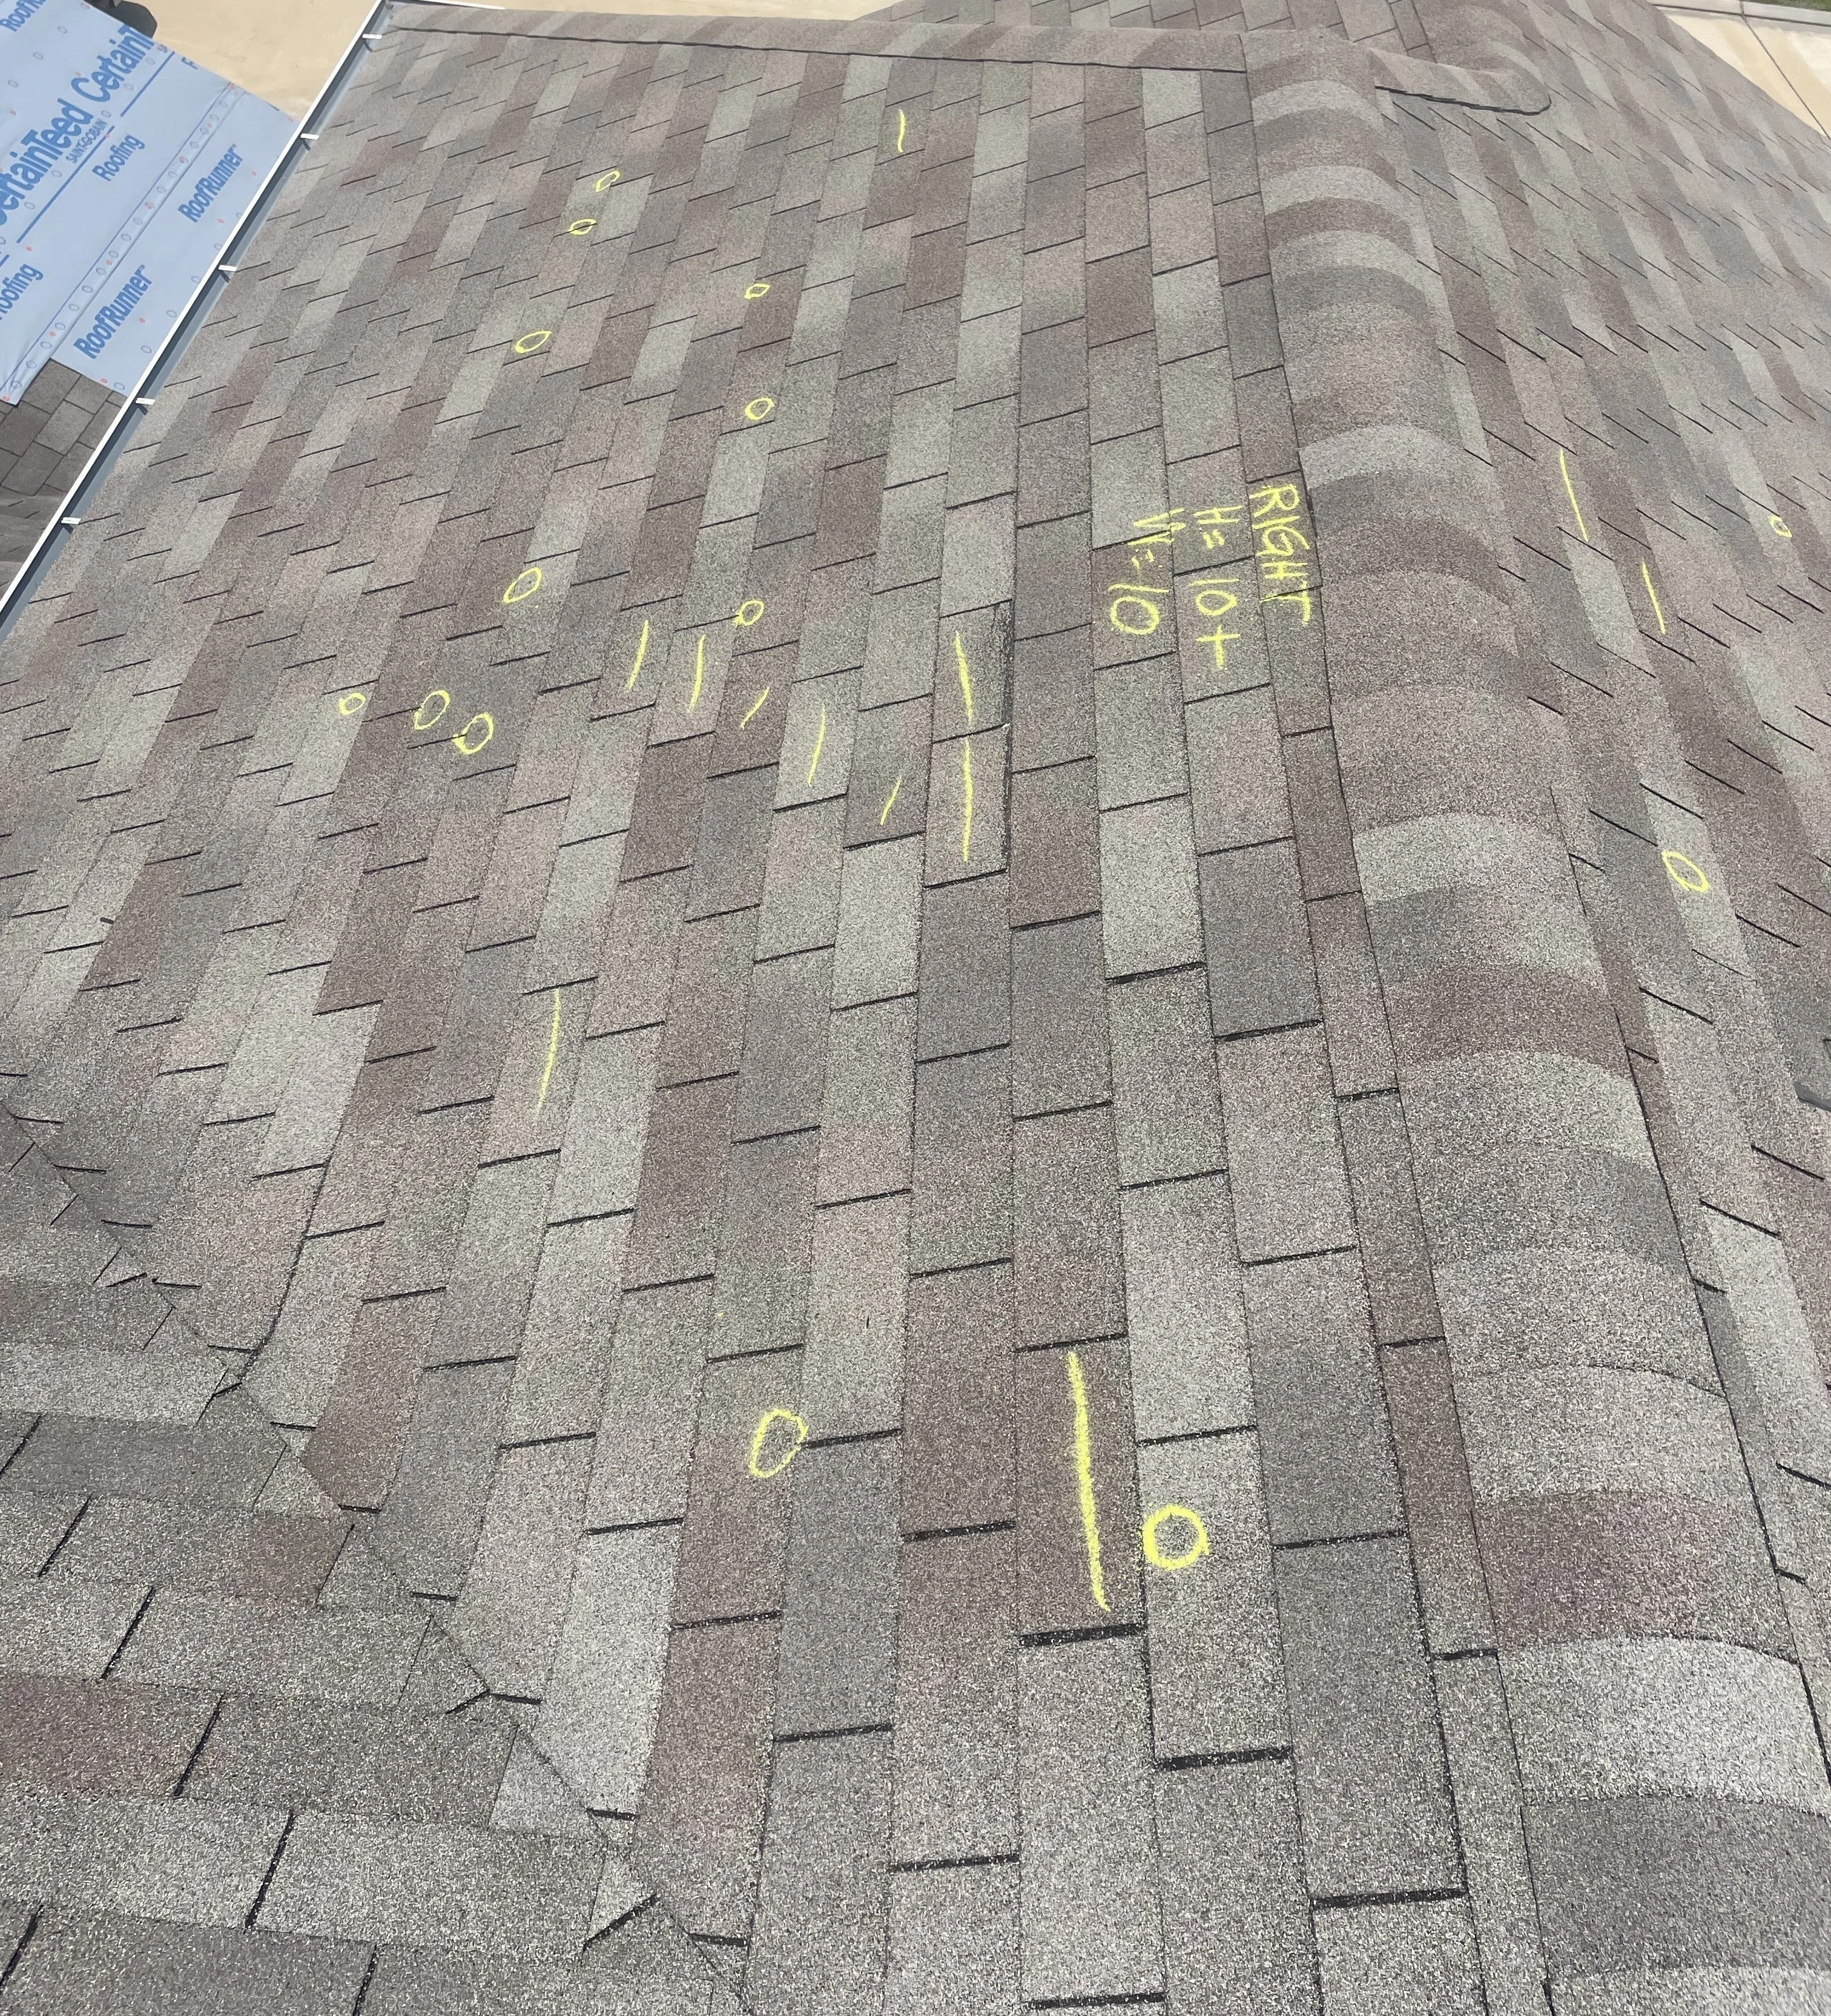
Why a Professional Inspection Comes Before Assumptions
Understand What Your Policy May Pay
Your Deductible
The deductible is what you owe before insurance payment applies. In Texas, it may be a flat dollar amount or a percentage of your home's insured value. A percentage deductible can be significantly larger than homeowners expect, run the math before making financial decisions.
Replacement Cost Value (RCV)
RCV policies generally pay the full cost to replace damaged materials at today's prices, minus your deductible. The carrier often holds back a portion, called recoverable depreciation, until the work is complete and you submit proof.
Actual Cash Value (ACV)
ACV policies deduct depreciation based on the roof's age and condition. The older the roof, the lower the payout. There is no recoverable depreciation on an ACV policy, what the estimate shows is typically what you receive.
Exclusions and Deadlines
Most Texas policies exclude damage caused by lack of maintenance, faulty installation, or gradual deterioration. There is also a deadline for reporting a loss, missing it can give the carrier grounds to deny the claim entirely.
Step 4
File the Claim With Facts, Not Guesswork
Once an inspection confirms credible storm damage and the repair or replacement cost appears to exceed your deductible, contact your carrier to begin the claim.
Report the Loss
Be accurate and direct. Share the date of loss, describe what you observed, and provide the records you gathered. Exaggerating or guessing at damage scope creates problems later. Your inspection report is your evidence. Let it do the talking.
Adjuster Inspection
The carrier will assign a claim number and schedule an adjuster to inspect the property. Have your inspection documentation ready. A contractor can be present during the adjuster visit. That is not unusual, and it means someone who knows what hail bruising looks like is on the roof beside the adjuster.
Review the Scope
When the estimate arrives, read the line items, not just the check amount. Confirm it addresses roofing materials, tear-off, underlayment, flashing, vents, drip edge, gutters, interior water damage where applicable, debris removal, and any code-required upgrades. Missing line items are common and can be supplemented.
Review the Estimate Line by Line
Know Before You File
When a Claim May Not Be the Right Move
Small Repairs Below the Deductible
If the repair cost is less than your deductible, filing a claim produces no payout and adds a claim to your policy record. A direct roof repair is often the cleaner path.
Aging Roofs at End of Life
A roof that has simply reached the end of its expected lifespan is not a covered loss. Carriers can, and do, deny claims on roofs where deterioration is the primary cause of failure.
Maintenance-Related Leaks
A leak caused by worn sealant around a pipe boot, failed caulking at flashing, or missing gutter sections is a maintenance issue. These are common fixes, and they do not require a claim.
Multiple Claims in Short Windows
Filing frequently can affect your renewal terms or premium. If a storm caused genuine covered damage, file. If the damage is marginal, weigh the cost of a claim against the cost of a direct repair.
Avoid These Common Claim Mistakes
Waiting Too Long
Texas weather can turn minor roof damage into moisture intrusion, decking deterioration, and mold concerns within weeks. After a significant storm, especially if neighbors are getting roofs replaced or you notice vehicle or screen damage. Schedule an inspection promptly.
Signing an Assignment of Benefits
Some contractors ask homeowners to sign over their insurance rights before work begins. In Texas, this can limit your ability to dispute the claim or change contractors. Read anything you sign carefully before a claim is filed.
Accepting an Incomplete Estimate
If the adjuster's estimate misses line items, missing drip edge, no code upgrade allowance, gutters excluded, those items can be supplemented. Do not assume the first number is the final number. Compare it against your contractor's scope.
Choosing a Contractor Based on Price Alone
Post-storm markets attract out-of-state contractors who leave when the work dries up. Choose an insured, local contractor who will still be reachable when a warranty question comes up two years from now.
Straight from Google
What Texas Homeowners Have Said
Working with PPB Roofs & Restoration was a smooth process from start to finish. Communication was great the entire time, and they kept us updated throughout the project. The crew was professional, on time, and did an excellent job cleaning up afterward. The roof came out great and I’m very impressed. Definitely a company I would recommend to others.
 Miranda Gonzales
PPB Roof and Restoration were excellent on my roof replacement. They were not high pressure, nor did they try to up-sell on products I didn’t need. Their prices were more than fair. The entire process was easy and very straightforward. They completed our entire roof in one day. David my project manager and AJ the owner were both very helpful and responsive. We are very happy with the results and strongly recommend the company.
 Bert & Diane Molina
Ayden Diaz and Prime Property Builders offered a complimentary inspection of my roof when they were doing some repairs in my neighborhood. They were nice and honest. They did not find much problem with my roof except normal wears and some nail holes. They came back the other day and caulked the holes for free to prevent possible leaking as heavy rains forecasted to come next day! I do appreciate their honest, consideration, and community spirit! I would do business with them in the future.
 Xiao Wang
I was approached by several other roofing companies that did not help with my insurance claim. So, when AJ Diaz stopped by, it was difficult to believe that he would be different. However, he was very knowledgeable about the entire insurance process and about roofing products, so I let him start the process. I am very happy that I did. He walked me through every step of the process and kept me informed of where my claim stood and what I needed to do next. He was on-site during the insurance company inspection and helped me find an independent inspector when my claim went to arbitration. He was happy to take the time to answer all my many many questions. Once my claim was finally approved, he helped me select roofing products that were best for my house, had a good quality guarantee, and the color that I wanted. He was able to explain the difference in the products and how they were installed. So, I feel like I made an informed decision. I also had gutters replaced that made everything look so good with the new roof. See the pictures! AJ was also on-site during the installation and came back afterwards to make sure I was happy. I am so happy by the way everything turned out. I highly recommend him and his company.
 Carol Sumrall
I am highly satisfied with the work completed by this company in the Houston area. From initial consultation through project completion, the entire process was managed with professionalism, efficiency, and attention to detail. What distinguished their service was the level of support provided after the installation. The team remained proactive in their follow-up, ensuring that all aspects of the project were functioning properly and that I was fully satisfied with the outcome. I would confidently recommend their services to anyone in Katy or the greater Houston area seeking high-quality roofing solutions and reliable, customer-focused service.
 Avery Callejo
Extremely happy with the service provided by Ayden and PPB PATIO & ROOF folks. Very reliable and honest. Will definitely recommend them to anyone looking to replace their roof.
 KaiSoon Tan
Questions Homeowners Ask Before Filing
Still have a question?
Ask the team directly. We pick up, and a straight answer costs nothing.
How do I know if my damage is covered?
Can I get a roof replaced for free through insurance?
What if the adjuster misses damage?
How long do I have to file after a storm?
Should I get my own inspection before calling my insurance company?
We Are on Your Side From Inspection to Completion
A storm may be outside your control. Your next step is not.
-
Insured contractor
Documentation available on request
-
Free storm damage assessments
Detailed photos and written report included
-
On-site during adjuster inspections
We know what to look for
-
Serving Richmond, Sugar Land, Katy, and Greater Houston
Local and reachable after the job closes